
What Happens if You Die Before Using Any of the Benefits in a Hybrid Life and Long Term Care Insurance Policy? – Long Term Care University
Long Term Care University – Question of the Month – 10/15/26
By Aaron Skloff, AIF, CFA, MBA
Q: We read the Long Term Care University article, ‘Traditional Versus Hybrid Life and Long Term Care Insurance’ and prefer the Hybrid Long Term Care Insurance (LTC) policy. Can you explain what minimum death benefit and residual death benefit are?
Overview. Hybrid policies provide long term care benefits if you need long term care, a death benefit if you die without needing LTC, or both if you need a limited amount of LTC.
The Problem – Not All Versus Hybrid Life and Long Term Care Insurance Death Benefits Are the Same
Although all Hybrid LTC policies provide a death benefit if you do not need LTC, death benefits vary if you use the policy’s LTC benefits.
Click Here for Your Long Term Care Insurance Quotes
The Solution – Understand Your Policy’s Death Benefits
Hybrid Life and Long Term Care Insurance provides both life and long term care benefits. Each $1 of long term care benefits reduces the death benefit (life insurance benefit) by $1. Some policies provide additional death benefits (DB). Selecting a policy with the right balance of each should be based on your personal needs. The three most common types of death benefits are described below.
Residual Death Benefit. The residual DB is paid even if you use all your LTC benefits.
Minimum Death Benefit. The minimum DB is paid even if you use all your LTC benefits.
No Minimum or Residual Death Benefit. If your use all of your LTC benefits, you will not have a DB.
What Happens if You Die Before Using Any of the Benefits in a Hybrid Life and Long Term Care Insurance Policy?
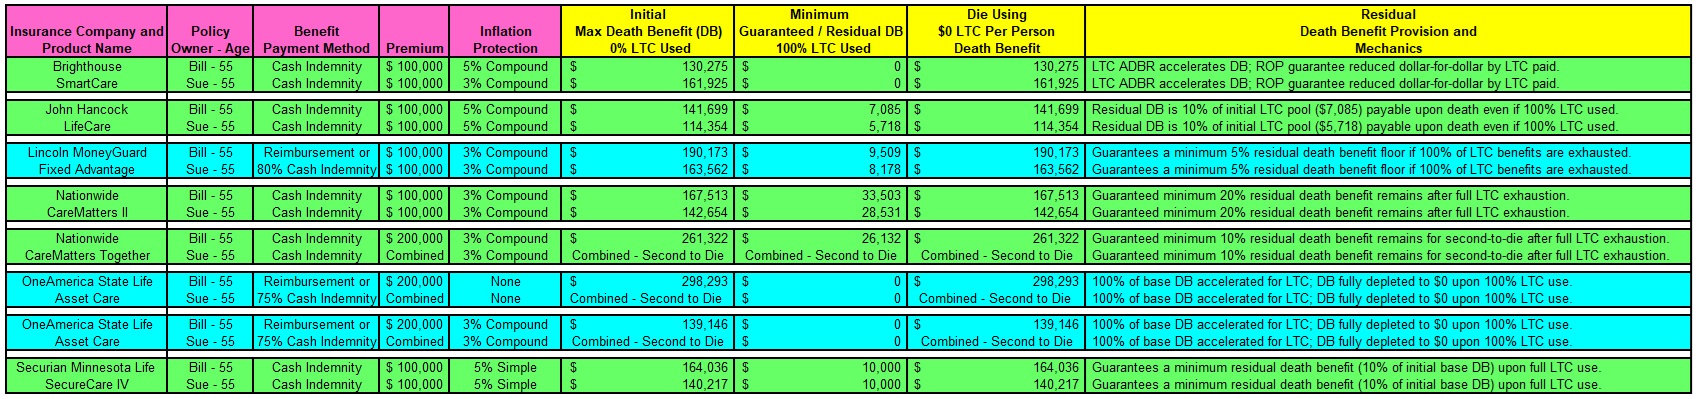
Let’s look at a husband and wife, Bill and Sue, who are each 55 years old and reside in Maryland. They each pay a $100,000 one-time premium ($200,000 combined with Nationwide CareMatters Together and OneAmerica State Life Asset Care) and are expected to need LTC in 25 years at the age of 80. They are comparing Hybrid policies that offer the largest LTC benefits with inflation protection (unless noted). See reimbursement policies in blue and cash indemnity policies in green in the chart below. What happens when they die? The following chart compares the top policies based on death benefits.
Brighthouse SmartCare. No Minimum or Residual DB policy. If they die before using any LTC benefits, Bill’s DB is $130,275, while Sue’s DB is $161,925.
John Hancock LifeCare. Residual DB policy. If they die before using any LTC benefits, Bill’s DB is $141,699, while Sue’s DB is $114,354.
Lincoln MoneyGuard Fixed Advantage. Residual DB policy. If they die before using any LTC benefits, Bill’s DB is $190,173, while Sue’s DB is $163,562. The policy also includes the Benefit Transfer Rider (BTR). It allows beneficiaries who are also policyholders, the ability to increase their benefits at the first death claim. Beneficiaries have three options: 1. Take the full death benefit. 2. Use the full death benefit to purchase more benefits on their own policy, 3. Take the partial death benefit and use the remainder to purchase more benefits on their own policy.
Nationwide CareMatters II. Minimum DB policy. If they die before using any LTC benefits, Bill’s DB is $ 167,513, while Sue’s DB is $ 142,654.
Nationwide CareMatters Together. Minimum DB policy. If they both die before using any LTC benefits, the second to die DB is $261,322.
OneAmerica State Life Asset Care without Inflation Protection. No Minimum or Residual DB policy. If they both die before using any LTC benefits, the second to die DB is $298,293.
OneAmerica State Life Asset Care with Inflation Protection.No Minimum or Residual DB policy. If they both die before using any LTC benefits, the second to die DB is $139,146.
Securian Minnesota Life SecureCare IV. No Minimum or Residual DB policy. If they die before using any LTC benefits, Bill’s DB is $164,036, while Sue’s DB is $140,217.
Click to Enlarge
Action Step – Compare Death Benefits Before Purchasing Your Policy
Death benefits can differ significantly between each insurance company’s policy. Work closely with an independent insurance expert to compare policies that meet your needs. Since premiums vary greatly based on age, health and marital status, request individualized quotes.
Aaron Skloff, Accredited Investment Fiduciary (AIF), Chartered Financial Analyst (CFA) charter holder, Master of Business Administration (MBA), is the Chief Executive Officer of Skloff Financial Group, a Registered Investment Advisory firm. The firm specializes in financial planning and investment management services for high net worth individuals and benefits for small to middle sized companies. He can be contacted at www.skloff.com or 908-464-3060.

Click Here for Your Long Term Care Insurance Quotes
Frequently Asked Questions
Q: What happens to a hybrid life and long-term care insurance policy if I die before ever needing long-term care?
If you pass away without using any long-term care benefits, a hybrid policy ensures that your named beneficiaries still receive a guaranteed income-tax-free death benefit. Unlike traditional standalone long-term care insurance—where premiums paid are entirely lost if you never need care—hybrid policies function similarly to permanent life insurance by returning value to your heirs in the form of a death benefit.
Q: What is the difference between a minimum death benefit and a residual death benefit in a hybrid policy?
The minimum death benefit is the guaranteed payout your beneficiaries receive if you never utilize any long-term care benefits over the life of the policy. Conversely, a residual death benefit is a small, guaranteed minimum payout that remains intact for your heirs even if you end up exhausting a significant portion or nearly all of your pool of long-term care benefits.
Q: Are hybrid long-term care insurance death benefits always paid out as a lump sum?
While a lump-sum payout is the most common option chosen by policyholders, many hybrid policies offer beneficiaries flexibility in how they receive the death benefit. Depending on the insurance carrier and contract terms, beneficiaries may have choices such as structured periodic payouts or placing the funds into an interest-bearing account, much like traditional life insurance policies.
Q: How does using long-term care benefits impact the final death benefit paid to my heirs?
When you draw upon your hybrid policy’s long-term care pool to pay for assisted living, nursing home care, or home health care, those withdrawals typically reduce the remaining death benefit dollar-for-dollar or based on specific policy acceleration factors. However, as noted, many policies guarantee a small residual death benefit so that your beneficiaries are not left with zero if you exhaust your care benefits.
Q: How do hybrid policies compare to traditional long-term care insurance regarding “use-it-or-lose-it” rules?
Traditional long-term care insurance operates on a strict “use-it-or-lose-it” model, meaning that if you die without needing care, all the cumulative premiums paid over the years are retained by the insurance company. Hybrid policies eliminate this primary consumer concern by blending life insurance and asset protection, ensuring that your premiums either pay for your long-term care expenses or guarantee a payout to your loved ones upon your passing.
Q: Can premium payments for a hybrid long-term care policy be made in a single lump sum or through installments?
Hybrid insurance policies offer flexible funding structures, allowing buyers to pay via a single, large single-premium payment or through structured multi-year premium installments (such as over 5, 10, or 20 years, or up to a specific age like 65). Regardless of whether you pay all at once or spread payments out, the core guarantees—including the death benefit for your beneficiaries if you don’t use care—remain protected according to the terms of your vesting and premium schedule.